
The Greater Vancouver Area stands among Canada’s most competitive and expensive real estate markets. The process of obtaining a mortgage for buying a home in Greater Vancouver resembles solving a financial enigma. The process of becoming a homeowner in this region faces special challenges because of home price appreciation and strict mortgage stress tests, as well as local programs and interest rate fluctuations.
This guide explains the most effective mortgage choices for Vancouver property buyers while showing how local regulations, together with property types, shape their mortgage opportunities.
What Makes the Vancouver Mortgage Market Unique
Two dominant elements shape the Vancouver housing market through its high property prices and shortage of available homes. Homebuyers in this market must deal with higher down payment requirements, together with tougher credit requirements, and extended financial planning needs. The current average home price in Metro Vancouver exceeds $1.2 million, with detached homes typically exceeding $2 million. The cost of condominiums stays relatively manageable while requiring excellent financial standing and solid credit scores from buyers.
The mortgage rules in Vancouver reflect the market’s high stakes, requiring buyers to clear both federal stress tests and lender-specific underwriting guidelines.
High-Value Markets and Loan Qualification Challenges
To secure a home loan in Vancouver, you must succeed in managing more than interest rates. Lenders conduct a thorough evaluation of the following factors:
- The Gross Debt Service (GDS) and the Total Debt Service (TDS) ratios
- Down payment size (especially for homes over $1M that require a 20% minimum)
- Credit score thresholds (720+ for best rates)
- Employment stability and income verification
- Property type and condition
The high price gap between Vancouver home values and resident incomes drives buyers to pursue co-borrowing with family members or seek alternative mortgage lenders to secure financing.
Fixed vs. Variable Rates in the Vancouver Context
The selection between fixed and variable mortgages in Vancouver depends mostly on how much risk you are willing to take.
- Homeowners who need predictable payments in an unpredictable market prefer fixed-rate mortgages.
- The benefits of variable-rate mortgages include initial cost savings, yet homeowners face potential rate increases that may increase their monthly payments in Vancouver’s costly environment.
The expensive nature of Vancouver real estate means that even a 0.25% change in mortgage rates produces substantial monthly mortgage costs. Homeowners now select hybrid mortgages because they provide both fixed interest rate stability during the initial part of the term and adjustable interest rates during the remainder of the loan period.
Special Considerations for Condos vs. Detached Homes
The process of buying a condo or detached home within Greater Vancouver leads to significantly different mortgage experiences for buyers.
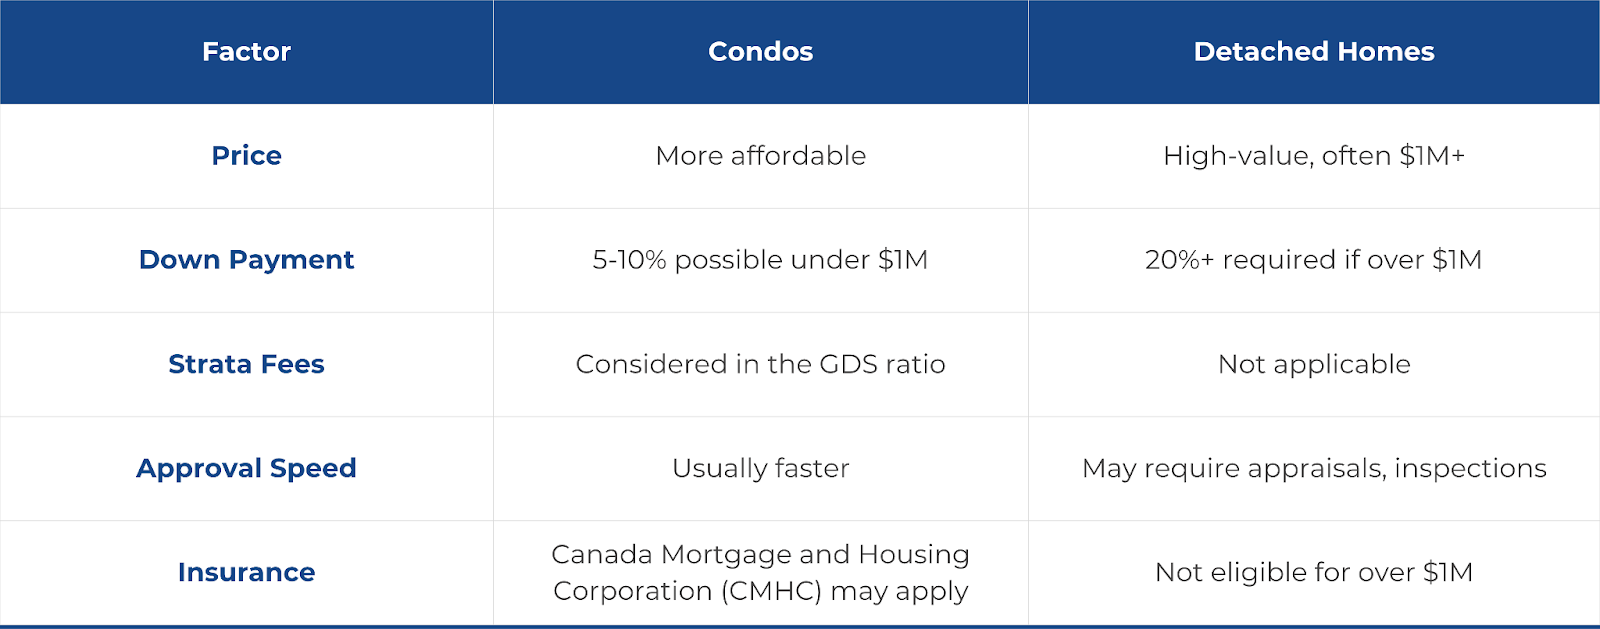
The typical starting point for first-time buyers involves purchasing condos in Burnaby, Richmond or New Westminster before moving to higher-cost properties.
First-Time Buyer Programs and Local Incentives
The first-time buyer mortgage programs operating in Vancouver assist new homebuyers with market entry.
- The First-Time Home Buyers’ Program (BC) eliminates property transfer tax for homes priced under $500,000 and offers partial relief up to $525,000.
- The Home Buyers’ Plan (HBP) allows you to access $35,000 in tax-free money from your Registered Retirement Savings Plan (RRSP) funds through this program.
- The First Home Savings Account (FHSA) functions as a registered account that allows users to save up to $8,000 annually and reach a maximum of $40,000 while providing tax benefits on contributions and withdrawals for home purchases.
- Municipal Programs like the Affordable Home Ownership Program (AHOP) offer affordable housing options through shared-equity models below market value to homebuyers.
The strategic application of these choices enables you to minimize your expenses for paying out of pocket.
Working with Vancouver-Based Mortgage Brokers vs. National Lenders
Selecting between a mortgage broker and a national bank requires you to make several compromises.
Local Mortgage Brokers
- Mortgage seekers gain access to multiple lenders, including both private and alternative financial institutions.
- The advice provided by brokers focuses on Vancouver-specific zoning regulations as well as income requirements and British Columbia province mortgage rules.
- The approval process for self-employed and credit-challenged buyers has more lenient requirements from mortgage brokers.
National Bank Lenders
- Preferred client rates or perks may be available
- The approval process for existing customers at the bank is typically faster
- Strong digital platforms and mobile pre-approvals
A mortgage broker usually holds better negotiating power since they work with different lenders to discover specific loan products, such as extended amortization and interest-only payment options for investment properties.
Tips for Improving Approval Chances in a Competitive Market
The current competitive market and tightened loan requirements require specific strategies for boosting mortgage approval chances. The following steps will improve your chances of getting approved for a mortgage in today’s competitive market:
- Get pre-approved with a broker before house hunting
- Maintain a credit score above 700
- Minimize other debt (credit cards, car loans) to improve the TDS ratio
- Avoid major purchases or job changes during the process
- Consider co-signers or joint applications for higher-priced homes
- Use a mortgage affordability calculator to stay within budget
It is possible to increase your down payment in order to qualify for lower CMHC insurance premiums and better interest rates.
FAQs
- What mortgage options are available in Greater Vancouver?
The mortgage market provides fixed, variable and hybrid, as well as open, closed, and private options based on individual profiles and target goals. - How does Vancouver’s high home price affect mortgage qualification?
The need for a 20% down payment on properties above $1M, along with their exceeding traditional GDS/TDS thresholds, creates additional qualification difficulties. - Are there special mortgage programs for Vancouver first-time buyers?
Yes. BC offers the Property Transfer Tax Exemption and municipal affordable housing programs. The FHSA and HBP national options are available to first-time buyers. - Should I choose a fixed or variable rate in the Vancouver market?
Fixed-rate mortgages provide market stability during periods of volatility. The initial cost savings from variable rates come with increased risks when interest rates rise. A broker can help you determine the best mortgage choice based on your risk level. - What’s the minimum down payment for a Vancouver home?
The down payment requirements for home purchases are 5% for properties less than $500,000 and 5-10% for homes valued up to $1.5 million, while homes priced at $1.5 million and above need a minimum 20% down payment. - How do mortgage brokers in Vancouver differ from bank lenders?
A mortgage broker represents clients by accessing various lenders, while banks maintain exclusive control over their proprietary offerings. - Are there affordability incentives specific to British Columbia?
Yes, which includes the Property Transfer Tax exemptions, AHOP, and various city-level housing incentives. - Is it harder to get approved for a mortgage in Vancouver than in other cities?
Mortgage approval in Vancouver proves more challenging compared to other cities because of its high home prices, together with stringent approval requirements. - What should I consider when financing a condo vs. a house in Vancouver?
The purchase of a condo demands smaller initial payments but adds fees for strata management. The purchase of detached homes requires substantial down payments, together with home valuations. - How can I improve my chances of mortgage approval in a competitive market?
Start with getting pre-approved, then improve your credit score, pay down debts, and work with a broker who understands the local lending landscape.
Partner with a Local Expert for Long-Term Success
The mortgage environment in Greater Vancouver operates as an exclusive system that distinguishes itself from other Canadian regions. Buyers need more than traditional lending options because they require a strategy to navigate the high property values, along with unique regional programs and fast market movements in Vancouver.
Local Vancouver mortgage brokers serve as essential partners who guide clients in selecting their best Vancouver housing mortgage options and advise on fixed versus variable mortgage Vancouver choices and first-time buyer mortgage programs.Ready to explore your mortgage options? A local expert who understands Vancouver housing affordability will lead you through the entire process.


